
India’s power sector is moving through one of its busiest build-out phases in years. Grid expansion targets, manufacturing incentives, and a fast-growing renewable base are all converging at once, and that convergence is exactly what’s fueling the current infrastructure capex cycle India finds itself in. To really understand where this spending is headed, you have to look past the headline crore figures and study how EPC companies are structuring their growth internally. One thesis that keeps coming up in boardroom conversations is the “three-engine platform” model, where transmission, manufacturing expansion, and storage are treated as one connected growth engine instead of three unrelated business lines.
Did You Know? According to the IBEF, India’s power transmission and distribution sector is set for a sustained growth cycle, supported by an estimated Rs. 9 trillion (US$ 94.32 billion) capital expenditure programme through 2032.
It is pushed along by grid modernization, renewable integration, and rising industrial power demand. Companies with order books spread across substations, manufacturing, and storage tend to hold up better through demand swings than firms betting on a single segment.
What Is Driving India’s Current Infrastructure Capex Cycle
Capex cycles almost never move in a straight line. They usually form around one or two anchor drivers and then widen out as private demand starts catching up with public investment. What makes the infrastructure capex cycle India is going through right now a little different is that it’s being pulled from several directions at the same time, not just one policy push.
On one end, state and central utilities keep awarding large transmission and substation contracts to keep the grid stable as renewable capacity gets bolted on at scale. On the other end, private players, manufacturing plants, data centers, and industrial parks, are commissioning their own captive power and grid-connectivity projects. A few things stand out when you look at where this demand is actually coming from:
- Utility (PSU) tenders remain a steady base, but they’re no longer the whole story
- Independent power producers are awarding substantial substation and switchyard work as renewable capacity scales
- Private industrial customers now account for a growing share of order inflows, sometimes more than half at established EPC players
- Voltage requirements are broadening too, with active demand spanning 66 kV all the way to 765 kV
That spread across customer types is really what gives this cycle its staying power.
The Three-Engine Platform Thesis
When executives at power EPC companies talk about long-term positioning, the three-engine framework comes up a lot: transmission, manufacturing, and storage. The firms that seem to be handling this cycle best aren’t running these as separate divisions. They’re running them on one platform, where each engine feeds the other two.
Engine One: Transmission
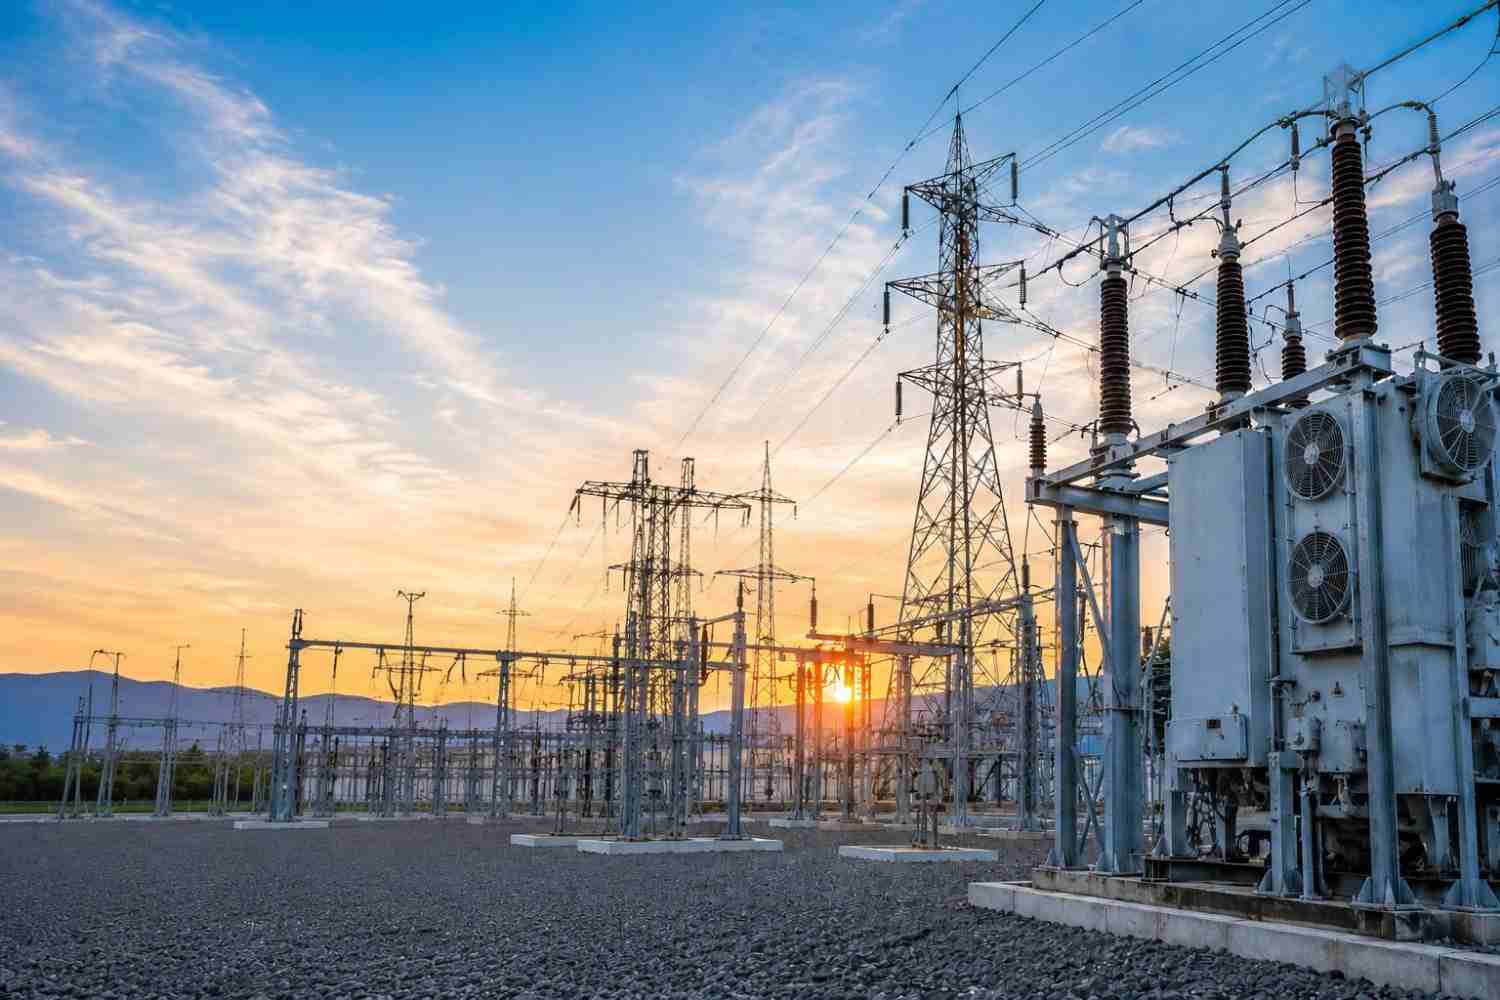
Transmission is still the backbone here. High-voltage substation and switchyard projects, everything from 66 kV distribution work up to 765 kV extra high voltage substations, make up the largest and most visible chunk of most order books. These projects matter because they’re what actually moves renewable power from where it’s generated to where it’s consumed, and they keep the grid from wobbling as load patterns get less predictable. Recent contract wins in this space, spread across utility, IPP, and industrial buyers, show just how broad transmission demand has become.
Engine Two: Manufacturing Expansion
The second engine is domestic manufacturing, things like switchgear, panels, and other power distribution equipment. Building this capacity in-house does two useful things. It cuts reliance on imported components at a time when global supply chains are still a bit shaky, and it improves project margins since more of the value stays inside the company instead of going to third-party vendors. This is also the engine most directly boosted by policy pushes around domestic manufacturing and self-reliance in electrical equipment.
Engine Three: Storage
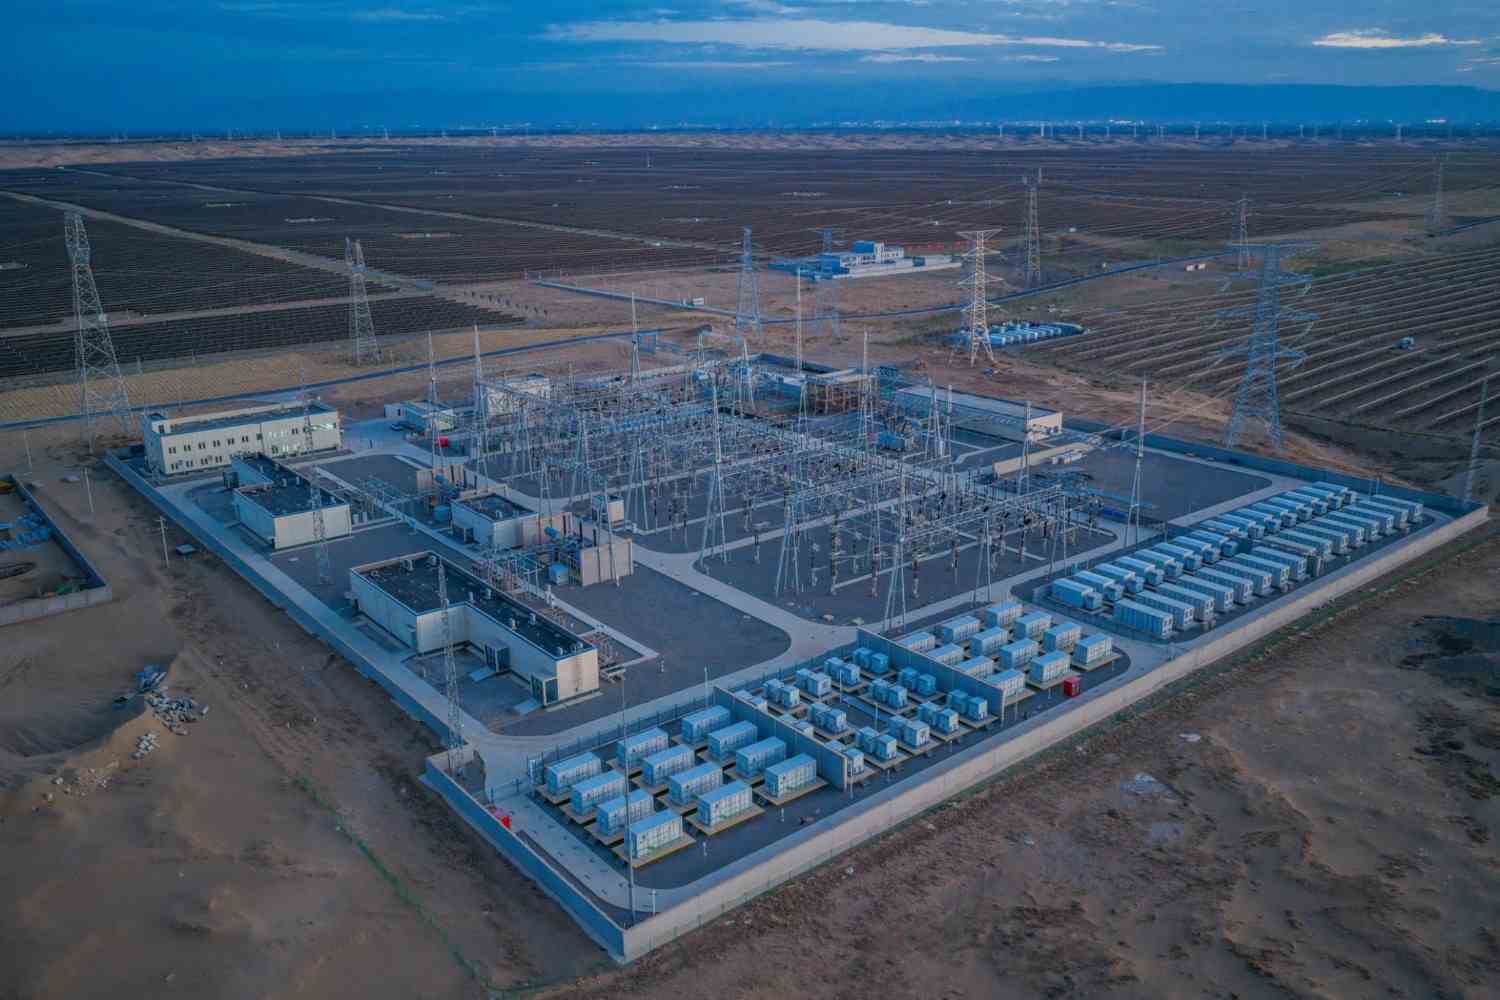
Storage is the newest of the three, but it’s growing the fastest. As solar and wind capacity keeps piling up, storage becomes necessary just to manage the intermittency and cut down on curtailment. EPC companies that can offer solar-plus-storage as one integrated package, rather than bolting storage on as an afterthought, are in a much better position to win the next wave of renewable capex, since more utilities and developers are now specifying storage right alongside generation in their tenders.
Order Book Trajectories and the Power Infrastructure Growth Cycle in India
Order books tend to tell you more about where things are heading than quarterly revenue does, simply because they signal demand before it shows up on the balance sheet. A few patterns worth watching:
- Transmission and substation orders across multiple voltage classes have kept flowing in from utility, IPP, and industrial customers alike
- Renewable EPC order books are increasingly bundling storage components rather than generation capacity alone
- Diversified order books, spread across all three engines, tend to smooth out the impact of a slow quarter in any one segment
This is fairly consistent with the broader power infrastructure growth cycle India is currently in, where capacity additions on the generation side are increasingly matched by investment in evacuation infrastructure and storage buffers. A company with exposure across transmission, manufacturing, and storage is naturally less rattled by a dip in any single line, since weaker transmission awards one quarter can be offset by manufacturing or storage momentum in another.
Why an Integrated EPC Business Model Matters Right Now
An integrated EPC business model gives a company control over more of the value chain at once: engineering, procurement, construction, manufacturing, and commissioning, all under one roof. That matters more today than it did a few cycles back, mainly because project timelines have gotten shorter while technical complexity has gone up. Utilities and private developers increasingly prefer one EPC partner who can execute end-to-end rather than juggling several specialized vendors, since a single point of accountability cuts down execution risk on large, high-value projects.
There’s a cost angle too. When manufacturing capacity sits inside the same group as project execution:
- Component lead times shrink, since there’s no third-party procurement cycle to wait on
- Pricing becomes less exposed to external supply shocks
- Quality control stays consistent across the manufacturing-to-commissioning chain
That combination matters a lot when project schedules are tight, and penalty clauses are baked into most utility contracts.
Simarpreet Singh, Group Executive Director and CEO of Hartek Group, has spoken to this directly, noting that securing large-scale transmission and substation projects reflects the ability to deliver complex solutions that India’s evolving energy infrastructure genuinely needs, and that wins across the EHV segment continue to strengthen the company’s position as the sector scales up.
Key Takeaways
- The current infrastructure capex cycle in India is being driven by multiple demand sources at once, not just utility tenders
- The three-engine platform thesis ties transmission, manufacturing, and storage together into one growth strategy rather than three separate business lines
- Diversified order books across these engines cushion against a slowdown in any single segment
- An integrated EPC business model improves execution reliability and cost control on large, complex projects
- Sustained power sector capex investment points to structural demand growth, not a temporary spending bump
Power Sector Capex Investment in India: What’s Actually Sustaining It
The power sector capex investment India is currently seeing doesn’t look like a short-term spike. A few structural factors point toward a multi-year cycle rather than a one-off surge:
- Peak electricity demand keeps climbing as industrial corridors, data centers, and electric mobility expand
- Green energy corridor projects and renewable targets require years of transmission build-out just to be fully absorbed
- Domestic manufacturing incentives are pushing equipment localization, which itself demands fresh capital investment in production capacity
Taken together, these factors suggest power sector capex investment India is channeling toward the grid will likely stay elevated for the rest of this decade, with the mix gradually shifting from pure generation capacity toward transmission, storage, and equipment manufacturing as the load-bearing pillars.
Building the Next Phase of India’s Power Grid Starts With the Right EPC Partner!
The infrastructure capex cycle India is riding through right now won’t be won by companies that treat transmission, manufacturing, and storage as separate bets. It’ll be won by the ones running all three as a single, connected platform, backed by real execution capability at scale. If you’re evaluating an EPC partner for your next transmission, substation, or storage project, look for a track record across all three engines, not just one. Reach out to Hartek Group‘s team to talk through your project requirements and see how an integrated EPC business model can de-risk execution on your next power infrastructure build.
FAQs
- What does the infrastructure capex cycle in India currently look like?
It’s a multi-year build-out phase shaped by grid modernization, renewable capacity additions, and rising industrial power demand, with spending spread across transmission, generation, and storage projects.
- What is the three-engine platform model in the power EPC sector?
It’s a business strategy where transmission, manufacturing, and storage function as connected growth engines instead of isolated business lines, letting a company capture demand across the entire power infrastructure value chain.
- Why does an integrated EPC business model matter for large power projects?
It puts engineering, manufacturing, and execution under one roof, which lowers coordination risk, shortens component lead times, and keeps accountability clear on complex, high-value projects.
- How does battery storage fit into the current capex cycle?
It helps manage the intermittency of solar and wind generation and cuts down curtailment, and it’s increasingly bundled with renewable EPC contracts rather than installed as a separate, standalone system.
- Is the current power sector capex investment cycle expected to continue?
Most signs point to yes. Rising peak demand, green energy corridor build-out, and domestic manufacturing incentives all suggest the cycle has more years left in it rather than tapering off soon.
Share:


